# Backtesting and Evaluation
In `skfolio`, portfolio construction methods produce **target weights** that specify
the allocation selected at each rebalancing date. Evaluating these allocations over
subsequent observations involves two separate modelling choices:
* whether to compute portfolio returns at fixed target weights throughout each
holding period or at weights that evolve with asset returns between rebalances
* whether to sum the resulting portfolio returns arithmetically or compound them
into a wealth index
The choice of weights determines the portfolio return series, while the accumulation
method determines cumulative returns and drawdown measures. The same target
allocations can therefore produce different performance statistics under these
conventions. The appropriate settings depend on the evaluation objective:
* **Allocation skill (ex-ante).** Estimate the expected return and risk attributable
to the target allocations selected by the portfolio construction process. The aim
is to evaluate the allocation decisions themselves, independently of subsequent
changes in weights caused by relative asset returns.
* **Expected performance of the implemented strategy.** Estimate the expected
return and risk of rebalancing to the target weights at scheduled dates and
allowing the resulting holdings to evolve with asset returns between those
rebalances. Turnover and transaction costs are computed relative to the previous
period’s ending weights, including drift, rather than its target weights.
* **Relative strategy performance.** Estimate the difference in expected
performance between portfolio strategies. The appropriate implementation
convention depends on whether the comparison concerns the target allocation
decisions or the strategies as they would be implemented between rebalances.
When strategies are evaluated on the same out-of-sample dates, common biases may
cancel and positively correlated sampling errors can reduce the uncertainty of
the difference.
* **Historical realization (ex-post).** Reconstruct the holdings, trades, wealth
and drawdowns that would have occurred along the observed return path under the
stated implementation assumptions.
The first three objectives involve estimating expected performance from
out-of-sample returns. The observed history is one finite realization of the process
generating returns, so these estimates may be biased and are subject to sampling
uncertainty.
In an ex-post evaluation, holdings, trades, wealth and drawdowns are reconstructed
along the observed return path under the stated implementation assumptions. A more
accurate reconstruction does not necessarily improve estimates of expected
performance on another sample of returns.
In `skfolio` two parameters control these modelling choices:
* `weight_drift` determines the weights used to compute each observation’s return.
With `False`, returns are computed at the **target weights (no drift)**, which
remain constant within each holding period. With `True`, each holding period
starts at the target weights, but the weights used for subsequent observations
evolve with asset returns until the next scheduled rebalance. Returns are therefore
computed from **drifted weights**.
* `compounded` determines how the resulting portfolio returns are accumulated. With
`False`, cumulative returns are an arithmetic sum. With `True`, they form a
compounded wealth index. This setting affects drawdown measures, but leaves the
underlying return series unchanged.
Both default to `False`. The default therefore evaluates **allocation skill (ex-ante)**
at target weights, consistent with the optimizer’s linear portfolio return definition,
and accumulates returns arithmetically.
## Choosing the settings
`weight_drift` and `compounded` are independent, and all four combinations are valid.
The table gives suggested settings for each evaluation objective.
#### Suggested starting points
| Objective | `weight_drift` | `compounded` |
|-------------------------------------------------------------------|--------------------------------------------------------------|----------------|
| Allocation skill (ex-ante), before transaction costs | `False`: target weights (no drift) | `False` |
| Expected performance of the implemented strategy | `True`: drifted weights | `False` |
| Relative strategy performance | `False`: target weights (no drift). `True`: drifted weights. | `False` |
| Historical realization (ex-post): wealth and percentage drawdowns | `True`: drifted weights | `True` |
`compounded` changes cumulative returns, drawdown measures and ratios based on
drawdowns. Measures computed from individual returns, such as mean return, variance,
VaR, CVaR, and the Sharpe and Sortino ratios, are unchanged, as are their sampling
variances.
`weight_drift` changes the underlying returns and can change both the bias and
sampling variance of performance estimates for the chosen evaluation objective.
Reconstructing holdings and trades more accurately does not necessarily improve
estimates of expected performance. An evaluation at target weights can have lower
mean squared error if its reduction in sampling variance outweighs its squared bias.
See [Estimating expected return](#weight-drift-mse).
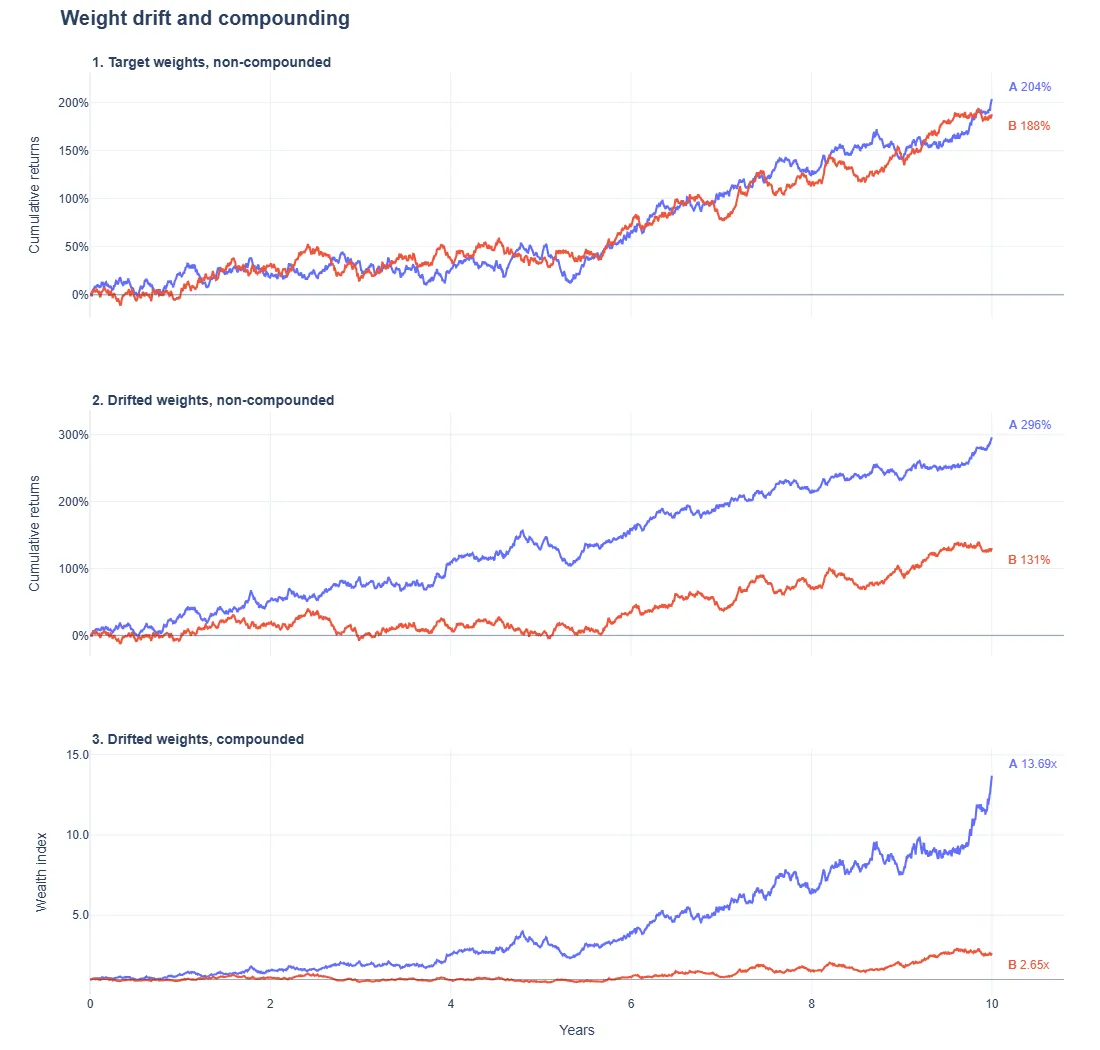
The figure below compares the effects of weight drift and compounding on two
illustrative ten-year paths from the same asset return model. The simulations use
equal target weights and annual rebalancing, with identical target allocations
across settings. The paths were selected to illustrate the differences. The
observed gaps do not estimate the typical effect of drift or compounding.
## How weight drift changes returns
Let $r_t$ be the vector of asset returns during observation $t$, and
$w_k$ the target weights set at rebalancing date $t_k$. The holding
period runs from $t_k$ to just before $t_{k+1}$. The equations in this
section describe returns before transaction costs and fees.
### Target weights (no drift)
With `weight_drift=False`, every observation within the holding period uses the same
target weights:
$$
r^{target}_t = w_k \cdot r_t,
\qquad t_k \le t < t_{k+1}.
$$
It is consistent with the optimizer’s linear portfolio definition and is the default
convention for evaluating allocation skill: the expected return and risk of the
target allocations are assessed independently of subsequent holdings drift.
Economically, it is equivalent to restoring the target weights after every
observation without charging for those within-period trades.
### Drifted weights
With `weight_drift=True`, let $u_t$ be the weights held at the start of
observation $t$. Each position grows with its asset’s return:
$$
r^{drifted}_t = u_t \cdot r_t,
\qquad
u_{t+1} = \frac{u_t \circ (1 + r_t)}{1 + u_t \cdot r_t},
\qquad u_{t_k} = w_k,
$$
where $\circ$ denotes element-wise multiplication. The weights reset to
the next targets at $t_{k+1}$.
For example, starting with 50% in each of two assets, if the first asset gains 10%
and the second is unchanged, the portfolio gains 5%. The next observation then starts
with weights of 52.38% and 47.62% under `weight_drift=True`, whereas an evaluation
at target weights continues to use 50% and 50% again.
If the first asset outperforms again, the portfolio with holdings drift has a higher
return than the target-weight portfolio because it now has greater exposure to that
asset. If relative performance reverses, it has a lower return. Momentum and
reversal can therefore affect the performance of the strategy under the two
modelling conventions.
The drift equation is self-financing, with changes in weights arising from asset
returns rather than from external cash entering the portfolio. A portfolio that is
rebalanced to its target weights can also be self-financing, since purchases can be
funded by sales of other assets. The conventions differ in whether target weights
are restored within the holding period.
`Portfolio` raises an error when wealth becomes non-positive because the weights for
the next observation are then undefined. This can occur, for example, in leveraged
or short portfolios following sufficiently large adverse returns.
## Turnover and transaction costs
At each scheduled rebalancing, turnover is computed from the difference between the
new target weights and either the previous target weights or the drifted ending
weights, depending on the evaluation convention.
Let $\tilde w_k$ denote the weights held at the end of holding period
$k$. The two conventions give
$$
\text{target turnover} = \|w_{k+1}-w_k\|_1,
\qquad
\text{executed turnover} = \|w_{k+1}-\tilde w_k\|_1.
$$
With `weight_drift=False`, `previous_weights` contains the previous portfolio’s
target weights. **Target turnover** measures the change between successive target
allocations.
With `weight_drift=True`, `previous_weights` contains the weights held at the end of
the previous holding period. **Executed turnover** measures the trades required to
move from these holdings to the new target allocation.
Drift reduces turnover when relative asset returns move the existing holdings toward
the next target and increases it when they move the holdings away from that target.
This can reduce trading for momentum strategies and increase it for reversal
strategies.
For any given pair of targets, the triangle inequality gives
$$
|\text{executed turnover} - \text{target turnover}|
\le \|\tilde w_k-w_k\|_1.
$$
With a sequential splitter, `cross_val_predict` passes each successful portfolio’s
`ending_weights` as `previous_weights` to the next fit when previous holdings are
needed. With drift disabled, `ending_weights` contains the target weights. With
drift enabled, it contains the weights held at the end of the period. Transaction
costs and turnover constraints are computed from these previous weights. Enabling
drift therefore makes the folds run sequentially and propagates ending weights even
without costs or a turnover constraint. When fits are independent, previous weights
are assigned to the predicted portfolios afterward for turnover and cost calculations.
When asset selection changes between rebalances, turnover and transaction costs are
calculated assuming full liquidation of positions in assets absent from the new
universe. In a pipeline, `set_output(transform="pandas")` preserves the asset names
needed to match previous holdings to the new selection. For assets absent from `X`,
`transaction_costs` must be a single rate applied to all assets or a dictionary
keyed by asset name.
For a direct `predict` call, transaction costs use the supplied `previous_weights`
under either drift setting.
The following example rebalances every five observations, applies a one-off cost
rate of 10 basis points on traded notional, and limits turnover in each asset to
30% of portfolio value at each rebalance:
```python
from skfolio.optimization import MeanRisk
holding_period = 5
tc_rate = 0.001
model = MeanRisk(
transaction_costs=tc_rate / holding_period,
max_turnover=0.3,
)
pred = cross_val_predict(
model,
X,
cv=WalkForward(train_size=252, test_size=holding_period),
portfolio_params={"weight_drift": True, "compounded": False},
entry_rebalancing_params={"max_turnover": None},
)
```
`max_turnover=0.3` is a per-asset constraint. Total portfolio turnover can exceed
30%. `entry_rebalancing_params` removes this constraint for the initial trade from
cash. The constraint applies from the second rebalance onward. This limit does not
apply to the assumed liquidation of positions outside the investment universe.
With transaction costs or turnover constraints, the next target allocation can also
differ depending on whether the optimization uses the previous target weights or the
portfolio weights at the end of the holding period. Evaluating the same sequence of
targets under both settings isolates the effect of holdings drift on returns and
turnover.
### Transaction cost convention
The optimizer expresses expected returns per observation, while transaction costs are
paid once when a rebalance occurs. To express the two quantities on the same basis,
a one-off transaction cost is divided by the expected holding period to obtain a cost
per observation. Portfolio evaluation uses the same convention.
See [periodicity convention](https://skfolio.org/user_guide/data_preparation.html.md#periodicity-convention) for the rationale and
conversion examples.
For a one-off transaction cost rate $c$ and an intended holding period of
$n$ observations, set `transaction_costs` to $c/n$, as in the example
above.
If turnover is $q_k$, each observation in that period is reduced by
$cq_k/n$. Over exactly $n$ observations, these deductions sum to
$cq_k$ in arithmetic-return units.
Charging the full transaction cost on the trade date would produce a different
observation-level return series and, after compounding, a different wealth path. It
would also change tail-risk and drawdown measures.
Both weight conventions use the same transaction-cost convention. If the actual
holding period contains $m$ observations, a fixed input $c/n$ deducts a
total of $mcq_k/n$ in arithmetic-return units. This matters for calendar-based
rebalancing and incomplete periods, where the number of observations varies.
`ending_weights` are the portfolio weights at the end of the holding period. With
`weight_drift=False`, they equal the target weights. With `weight_drift=True`, they
reflect the effect of asset returns through the final observation. They are calculated
before transaction costs and management fees because those costs reduce reported
portfolio returns but are not deducted from a modelled cash balance or individual
position.
Management fees remain based on the target weights selected for the holding period
rather than on subsequent changes in weights caused by asset returns.
## Return aggregation and compounding
For a given portfolio return series $r^{ptf}_t$, arithmetic accumulation is
$$
A_T = \sum_{t=1}^T r^{ptf}_t.
$$
Compounding produces a wealth index, expressed per unit of starting capital:
$$
W_T = \prod_{t=1}^T(1+r^{ptf}_t).
$$
`skfolio` reports the compounded series as this wealth index. Its total return is
$W_T-1$.
Use `compounded=True` for measures based on compounded wealth, including compounded
total return and percentage drawdown. This applies to both out-of-sample estimation
and historical reconstruction.
Changing `compounded` does not change the optimizer’s objective or the underlying
observation-level portfolio returns.
See [Data Preparation](https://skfolio.org/user_guide/data_preparation.html.md#data-preparation) for the discussion of simple and logarithmic returns.
For fixed targets within one holding period, before costs and fees, compounding
gives
$$
W^{target} = \prod_t(1+w_k\cdot r_t),
\qquad
W^{drifted} = \sum_i w_{k,i}\prod_t(1+r_{i,t})
+ 1-\sum_i w_{k,i}.
$$
The first expression describes restoring the target weights after every observation.
The second describes implementing the target allocation and holding the resulting
positions until the next scheduled rebalance. The final term is the implicit
zero-return cash position when the explicit asset weights do not sum to one.
Changing the order of asset returns within this holding period leaves both terminal
wealth values unchanged, provided wealth stays positive. At target weights, it also
leaves mean return and variance unchanged. With holdings drift, the portfolio
return series can change because holdings depend on earlier returns. Intermediate
wealth and drawdowns depend on return order in both settings.
## Configuring an evaluation
For a direct call to an optimizer’s `predict`, set the options in the optimizer’s
`portfolio_params`. For [`cross_val_predict`](https://skfolio.org/generated/skfolio.model_selection.cross_val_predict.html.md#skfolio.model_selection.cross_val_predict) and
[`online_predict`](https://skfolio.org/generated/skfolio.model_selection.online_predict.html.md#skfolio.model_selection.online_predict), pass them in the function’s
`portfolio_params`.
The following example applies three combinations of the settings to the same
historical data, with rebalancing every 21 observations. `X` contains asset returns
in decimal form, ordered by date, with one column per asset.
```python
from skfolio.datasets import load_sp500_dataset
from skfolio.model_selection import WalkForward, cross_val_predict
from skfolio.optimization import EqualWeighted
from skfolio.preprocessing import prices_to_returns
prices = load_sp500_dataset()
X = prices_to_returns(prices)
model = EqualWeighted()
cv = WalkForward(train_size=252, test_size=21)
target_evaluation = cross_val_predict(model, X, cv=cv)
drifted = cross_val_predict(
model, X, cv=cv, portfolio_params={"weight_drift": True, "compounded": False}
)
compounded_wealth = cross_val_predict(
model, X, cv=cv, portfolio_params={"weight_drift": True, "compounded": True}
)
```
`target_evaluation` evaluates the target weights and accumulates the resulting
returns arithmetically.
`drifted` starts each holding period at the same target weights but allows the
holdings to evolve with asset returns until the next rebalance. Its returns are also
accumulated arithmetically.
`compounded_wealth` uses the same holdings-based return construction as `drifted`
and compounds those returns into a wealth index.
The example illustrates the settings on historical data. It does not reproduce the
simulated figure. With daily equity data, 21 observations approximate a month. Use
calendar-based splits when rebalancing must occur on specific dates.
Each walk-forward call returns a [`MultiPeriodPortfolio`](https://skfolio.org/generated/skfolio.portfolio.MultiPeriodPortfolio.html.md#skfolio.portfolio.MultiPeriodPortfolio)
containing one [`Portfolio`](https://skfolio.org/generated/skfolio.portfolio.Portfolio.html.md#skfolio.portfolio.Portfolio) per test period.
`weight_drift` applies to each child portfolio. `compounded` applies to both
the children and the resulting `MultiPeriodPortfolio`. Function-level values
override the optimizer’s `portfolio_params`. Omitted values are inherited. See
[Cross-Validation Prediction](https://skfolio.org/user_guide/model_selection.html.md#cross-validation) for the complete routing rules.
`compounded` can also be changed after construction. To compound the existing
`drifted` return series without repeating the evaluation, use:
```python
drifted.compounded = True
drifted.plot_cumulative_returns()
```
This changes the aggregate object’s cumulative returns and drawdown measures. Each
child portfolio has its own `compounded` setting. `weight_drift` is fixed at
construction because changing it would change the portfolio return series.
### Holding periods and validation
A direct `predict(X)` call treats all of `X` as one holding period. With drift
enabled, the portfolio starts at its target weights and positions are held throughout
that window. In a walk-forward evaluation, each test period starts at its predicted
target weights. The length of the test period therefore sets the interval between
scheduled rebalances.
Different validation schemes can represent different types of evaluation path:
* [`WalkForward`](https://skfolio.org/generated/skfolio.model_selection.WalkForward.html.md#skfolio.model_selection.WalkForward) produces one sequential path.
* [`online_predict`](https://skfolio.org/generated/skfolio.model_selection.online_predict.html.md#skfolio.model_selection.online_predict) builds a path from a single
stateful estimator updated with `partial_fit`. See [Online Learning](https://skfolio.org/user_guide/online_learning.html.md#online-learning).
* [`MultipleRandomizedCV`](https://skfolio.org/generated/skfolio.model_selection.MultipleRandomizedCV.html.md#skfolio.model_selection.MultipleRandomizedCV) runs walk-forward
evaluations on randomly selected asset subsets and, optionally, contiguous time
windows.
* [`CombinatorialPurgedCV`](https://skfolio.org/generated/skfolio.model_selection.CombinatorialPurgedCV.html.md#skfolio.model_selection.CombinatorialPurgedCV) evaluates combinations of
test blocks and can train on observations later than a given test block. Its
reconstructed paths therefore do not represent strictly forward historical
simulations.
See [Cross-Validation Prediction](https://skfolio.org/user_guide/model_selection.html.md#cross-validation) for purging, embargoing and supported splitters.
## Estimating expected return
The sample means of the portfolio returns, computed with and without weight drift,
are two estimators of expected return. For the same target allocations, the bias
introduced by the choice of weights depends on the evaluation objective.
Before transaction costs, the return contribution from drift at observation
$t$ is
$$
d_t = r^{drifted}_t-r^{target}_t = (u_t-w_k)\cdot r_t.
$$
Its expected contribution to the sample mean over $T$ observations is
$\bar d = \frac{1}{T}\sum_{t=1}^T\mathbb{E}[d_t]$.
The expected transaction cost difference per observation, $b$, is the
expected cost of executed turnover minus the expected cost of target turnover.
* **Allocation skill (ex-ante).** Before transaction costs, `weight_drift=False`
evaluates the target allocations directly and introduces no bias from subsequent
holdings drift. `weight_drift=True` introduces drift contribution
$\bar d$.
* **Expected performance of the implemented strategy.** For expected net return,
`weight_drift=True` includes both holdings drift and the transaction costs
associated with executed turnover. `weight_drift=False` introduces bias
$b-\bar d$.
The expected gross-return difference between the two settings can be negligible
with frequent rebalancing. In two illustrative simulations, it is about
**0.2 bp p.a.** for a diversified 50-asset portfolio rebalanced weekly and about
**2% p.a.** for a concentrated four-asset high-volatility portfolio rebalanced
quarterly.
These are stylized simulations, not empirical estimates for particular asset
classes. They use equal target weights and geometric Brownian asset prices. The
[calculation appendix](#backtesting-calculation-details) gives the assumptions
and formulas.
The sample means also vary from one sample to another. Their sampling variances
measure this variability. In the same examples, drift increases the sampling
variance of the estimated gross mean by **less than 0.01%** for the diversified
portfolio and about **3%** for the concentrated high-volatility portfolio. Serial
correlation also affects sampling variance. A long-run variance estimate [1](#id3)
accounts for dependence between observations.
Mean squared error (MSE) combines squared bias with sampling variance.
$V_{\mathrm{target}}$ and $V_{\mathrm{drifted}}$ denote the sampling
variances of the two estimated net means. When the drifted mean is unbiased for
the implemented strategy’s expected net return under the return model, the MSEs
are
$$
\operatorname{MSE}_{\mathrm{target}}=(b-\bar d)^2+V_{\mathrm{target}},
\qquad
\operatorname{MSE}_{\mathrm{drifted}}=V_{\mathrm{drifted}}.
$$
The estimate at target weights has lower MSE when its reduction in sampling variance
exceeds its squared bias. Including holdings drift can also reduce sampling variance,
in which case the drifted estimate has lower MSE.
For the concentrated high-volatility example, a portfolio volatility of 66% p.a.
gives a standard error of about **30%** for the annualized target-weight mean over
five years ($66\%/\sqrt{5}$). When estimating the implemented strategy’s expected
gross return, its squared bias is only about **0.45%** of its sampling variance.
Its MSE is therefore close to that of the drifted estimate. With longer samples,
sampling variance decreases while a persistent bias remains.
## Appendix: Calculation details
The illustrative examples assume $N$ equally weighted assets, rebalanced
every $n$ observations, with $A$ observations p.a. Asset prices follow
geometric Brownian motions with equal exposure to a common market factor and
independent asset-specific shocks. Returns are independent across observations,
and transaction costs are excluded.
Let $\sigma_p$ be the annual portfolio volatility at target weights,
$\sigma_\epsilon$ the annual asset-specific volatility, and $s$ the
standard deviation of annualized expected arithmetic asset returns.
With $h=(n-1)/A$, the annualized expected gross drift contribution
$\bar d_{\mathrm{ann}}$ and relative change in sampling variance
$\gamma$ are, to leading order,
$$
\bar d_{\mathrm{ann}} \approx \frac{h s^2}{2},
\qquad
\gamma \approx
\frac{h(N-1)\sigma_\epsilon^4}{2N^2\sigma_p^2}.
$$
The variance change $\gamma$ is measured relative to the sampling variance
of the estimated gross mean at target weights.
* **Diversified weekly-rebalancing example.** $N=50$, $n=5$,
$A=252$, $\sigma_p=15\%$, $\sigma_\epsilon=21\%$
and $s=5\%$.
* **Concentrated high-volatility quarterly-rebalancing example.**
$N=4$, $n=91$, $A=365$, $\sigma_p=66\%$,
$\sigma_\epsilon=87\%$ and $s=40\%$.
### References
* **[1]** Newey, W. K. and West, K. D. (1987). A Simple, Positive Semi-Definite, Heteroskedasticity and Autocorrelation Consistent Covariance Matrix. *Econometrica*, 55(3), 703-708.